


Most New Jersey retirees assume Florida is automatically cheaper. The honest answer is more interesting: it depends on your income, your NJ home, and what you value.
Here is an illustrative annual comparison for a retired couple selling a New Jersey home and buying in Stillwater, a 55+ golf community in St. Johns County.
The Assumptions
- A married couple, both 62 or older
- NJ home: $650,000, paid off, sold and replaced with a Stillwater home at about $400,000 (recent median sold price: $399,540), paid in cash
- Social Security excluded from the NJ income tax picture, since NJ doesn’t tax it
- Figures are illustrative estimates, not quotes
What Changes at the Tax Level
- Social Security: exempt in New Jersey and in Florida
- NJ pension, IRA, and 401(k) income: up to $100,000 excluded for couples 62+ with total income of $100,000 or less. The exclusion shrinks between $100,000 and $150,000 and is gone above $150,000
- Florida: no state income tax on any of it
- Property taxes: New Jersey’s median bill runs roughly $8,000 to $9,500, among the highest in the country. A $650,000 NJ home often lands near $13,000 or more
Annual Housing Costs: Scenario A (Moderate Retirement Income)
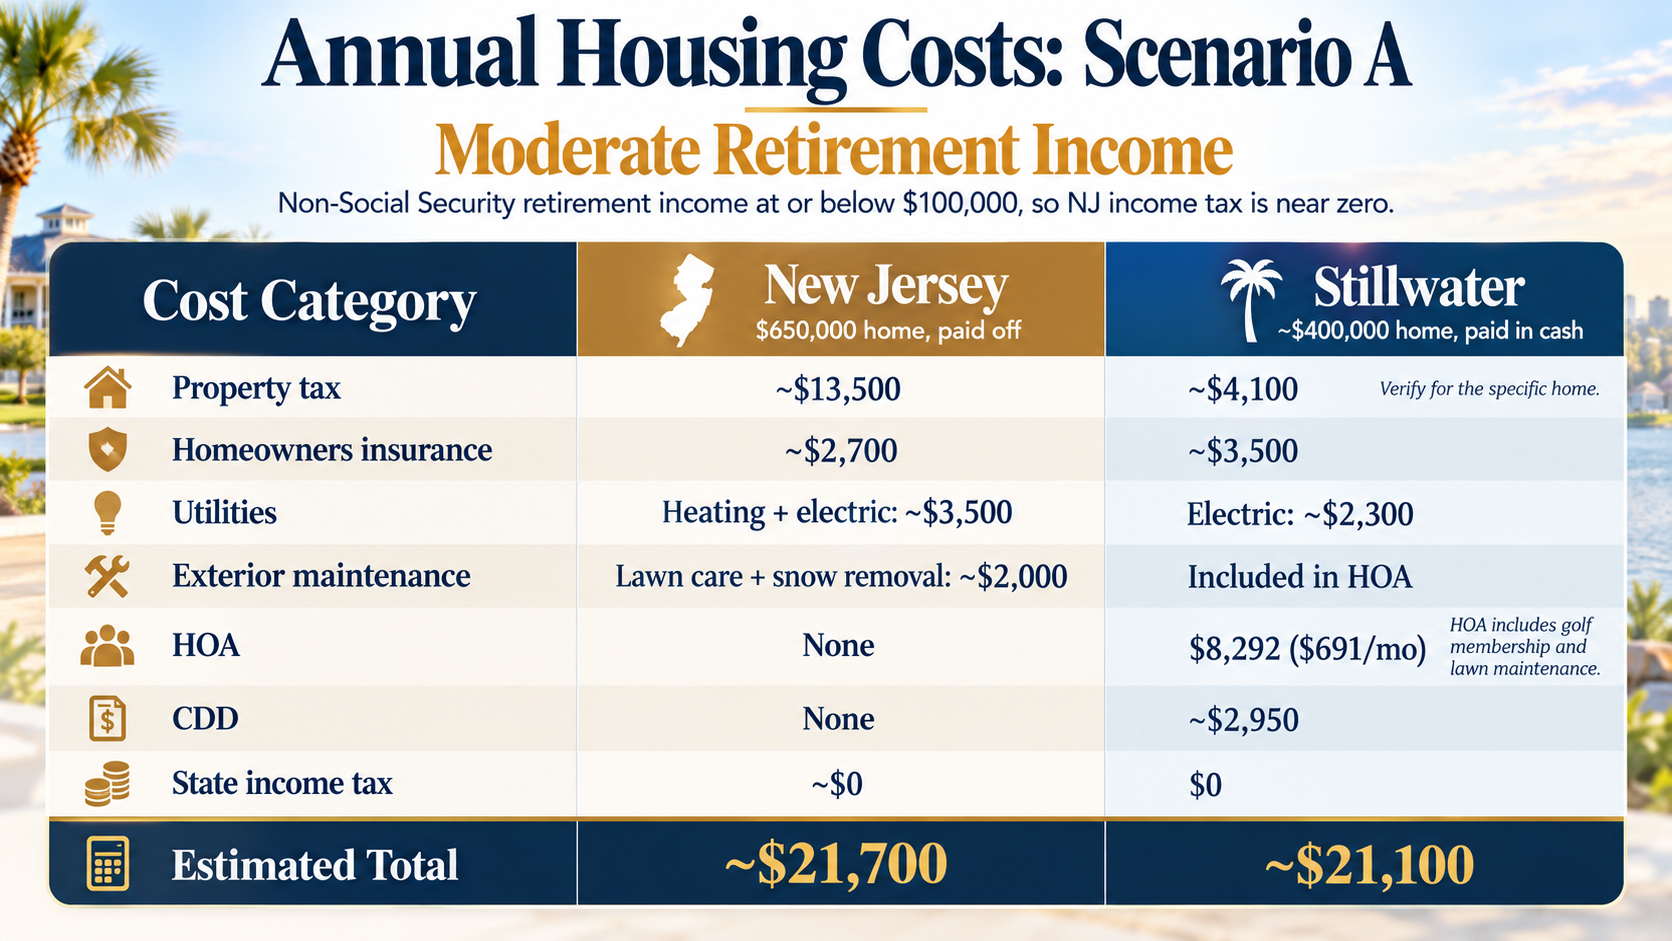
The honest takeaway: at moderate income, the two are roughly even on annual carrying costs. Stillwater’s high HOA offsets much of the property tax savings.
Where Stillwater Pulls Ahead
- Golf and lawn care are included. If you’d otherwise pay for a golf membership and yard service, the HOA replaces those costs rather than adding to them.
- Freed-up equity. Selling at $650,000 and buying at $400,000 can free roughly $200,000 to $250,000 after costs. At a 4% withdrawal rate, that supports about $8,000 to $10,000 a year of retirement income.
- Predictable property taxes. Florida’s Save Our Homes cap limits annual assessment increases for homesteaded homes to 3% or inflation, whichever is lower.
- Fewer winter costs. No snow removal and a shorter heating season.
Scenario B: Higher Retirement Income
Non-Social Security retirement income above $150,000, so NJ’s pension exclusion is gone.
- NJ state income tax could run roughly $5,000 to $6,500 or more per year, depending on deductions
- Florida income tax: $0
- That tax alone shifts the comparison clearly toward Florida, on top of the property tax difference
Retirees with large IRA balances and required minimum distributions often fall into this scenario, so check your projected income before assuming your NJ income tax is low.
When the NJ Side Is Cheaper Than You Think
- If your NJ property tax is closer to the state median (about $8,000 to $9,500), NJ carrying costs drop and Stillwater’s HOA looks heavier
- If you don’t golf, you’re paying for a bundle you may not use. Compare communities with lower HOAs, such as Del Webb Saint Johns
- Florida homeowners insurance usually runs higher than in New Jersey, and the figure above is only an estimate
What This Doesn’t Include
- Healthcare and Medicare supplement premiums, which vary by plan and state
- Groceries, dining, travel, and transportation
- Selling costs on your NJ home and New Jersey’s refundable sale withholding
- Capital gains tax on your NJ home sale above the federal exclusion
Who Stillwater Fits
- Retirees who golf regularly and want yard care handled
- Couples with a high-tax, high-value NJ home who can free up equity
- Retirees with larger pension or IRA income who lose NJ’s exclusion
- Buyers who want new construction in a gated 55+ community
Who Should Compare Other Communities
- Non-golfers with moderate income and a modest NJ property tax bill
- Buyers focused on the lowest possible monthly carrying cost
The Bottom Line
Moving from New Jersey to Stillwater doesn’t automatically cut your annual housing costs. For a moderate-income couple it can be close to a wash year to year, with the real advantages in freed equity, included golf and lawn care, and fewer winter costs. For higher-income retirees, the New Jersey income tax and property tax add up quickly.
Run your own numbers before deciding, using your NJ tax return, your projected retirement income, and the actual Stillwater HOA, CDD, and insurance quotes.
Want a Personalized Budget Comparison?
I can pull current Stillwater listings, verify HOA, CDD, and insurance figures, and connect you with a CPA who can model your NJ and Florida tax picture.
Call or text Gail DeMarco: 904-640-8000
Best St. Johns County 55+ Community & Relocation Specialist
Serving Stillwater, Del Webb communities, Nocatee, RiverTown, and all of St. Johns County, FL
All figures are illustrative 2026 estimates based on public listing data, published New Jersey tax rules, and local market sources. Property tax, insurance, and utility costs vary significantly by address. This article is for informational purposes only and is not tax, legal, or financial advice. Consult a CPA and a licensed insurance agent before making decisions.