Buying a home in St. Johns County, Florida doesn't always require a 20% down payment. For eligible military buyers and first-time buyers, VA and FHA loans can make homeownership more accessible.
But these programs work very differently. Here's what buyers should know before choosing a loan.
VA Loans: A Major Advantage for Eligible Buyers
For eligible veterans and service members, a VA loan can be one of the most powerful home-buying tools available.
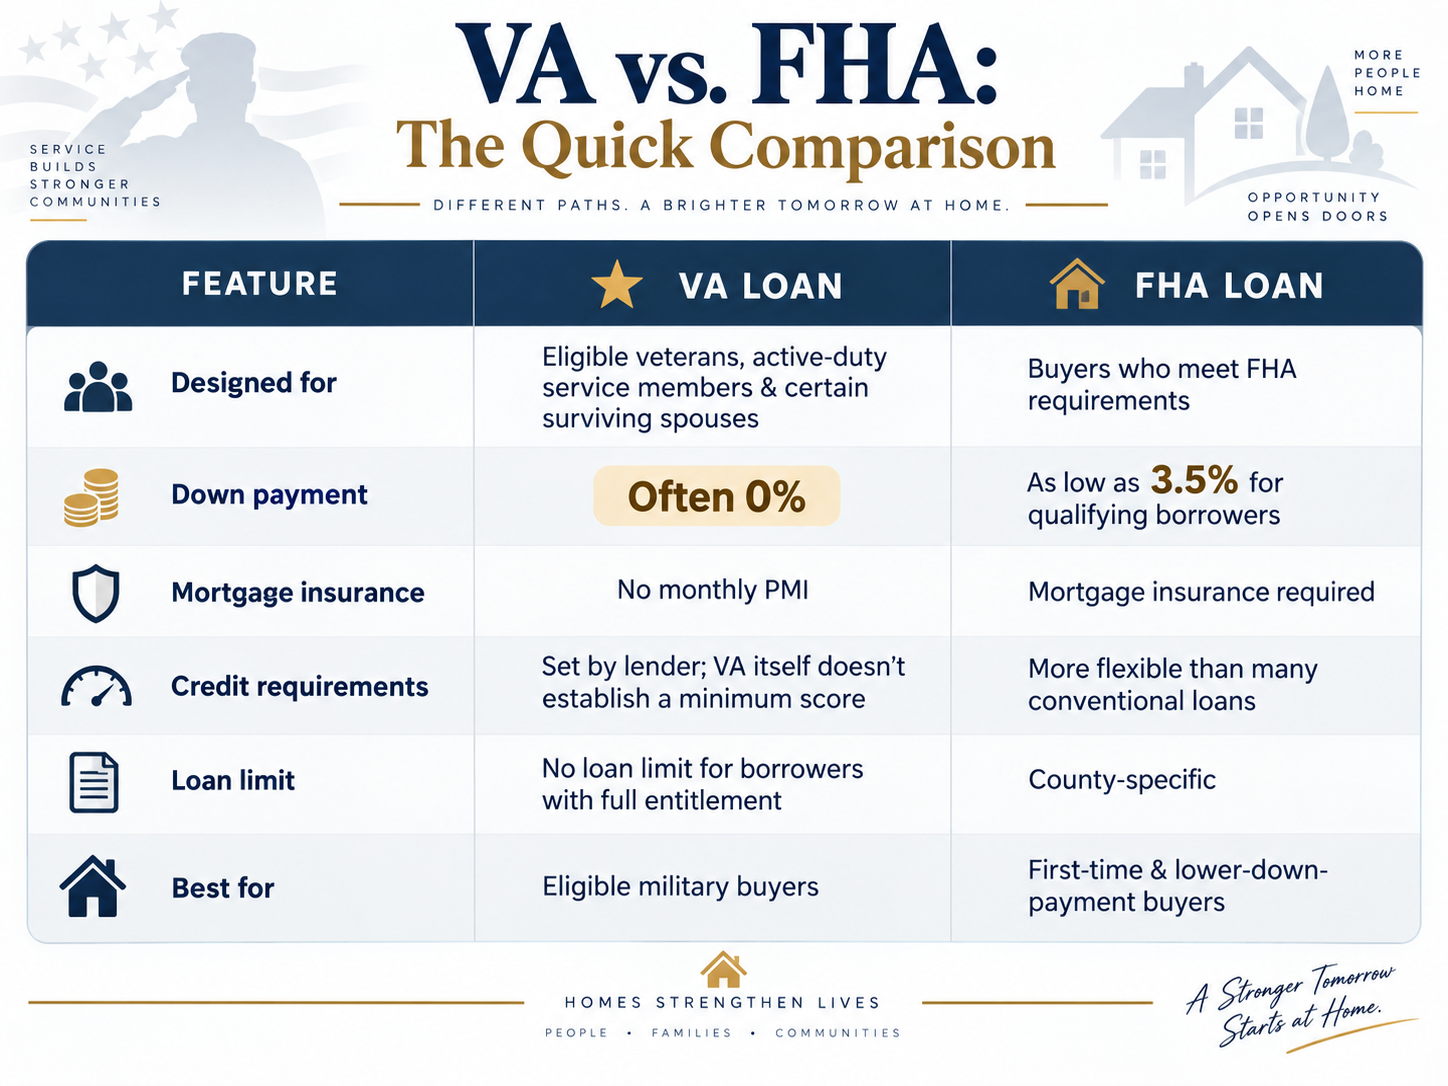
With full VA entitlement, eligible borrowers generally aren't subject to a VA loan limit. That doesn't mean you can borrow any amount regardless of income—the lender still evaluates your income, credit, debts, assets, and the property's value.
Another major advantage: VA loans don't require monthly private mortgage insurance (PMI).
That can make a significant difference in the monthly payment compared with some low-down-payment alternatives.
VA borrowers should also remember that a VA funding fee may apply, although certain borrowers are exempt.
FHA Loans: An Option for First-Time Buyers
FHA loans are insured by the Federal Housing Administration and are popular with buyers who want a lower down payment or may not qualify for the best conventional financing.
In 2026, the FHA loan limit for a one-unit property in St. Johns County is $580,750, according to current HUD-based county loan-limit data.
FHA financing can require as little as 3.5% down for borrowers who meet the applicable credit requirements.
For example:
| Home Price | 3.5% Down Payment |
|---|---|
| $400,000 | $14,000 |
| $500,000 | $17,500 |
| $580,750 | $20,326 |
Remember: your down payment isn't your total cash needed to close. Buyers also need to budget for closing costs, prepaid expenses, inspections, and other transaction costs.
What About St. Johns County Home Prices?
This is where the loan limits become particularly important.
If you're shopping for a home around $400,000–$500,000, FHA financing can potentially fit within the 2026 St. Johns County one-unit loan limit.
But if you're looking at homes significantly above that price, you may need to consider other financing options or make a larger down payment.
VA buyers with full entitlement have more flexibility, subject to lender approval and their overall financial qualifications.
Don't Forget About Florida Insurance
Whether you're using VA, FHA, or conventional financing, don't overlook one of the biggest costs of owning a home in Florida: homeowners insurance.
Your insurance premium can vary substantially based on:
- Roof age and condition
- Construction type
- Property location
- Flood zone
- Wind-mitigation features
- Coverage amount
- Insurance carrier
A lower purchase price doesn't necessarily mean a lower monthly housing cost.
Before making an offer, get an insurance estimate and calculate your complete monthly payment, including mortgage, taxes, insurance, HOA and CDD costs when applicable.
VA or FHA: Which One Makes More Sense?
VA may be the better choice if you:
✔ Are eligible for VA financing
✔ Want to minimize your upfront cash
✔ Want to avoid monthly PMI
✔ Have sufficient VA entitlement
✔ Are purchasing a primary residence
FHA may be worth considering if you:
✔ Are a first-time buyer or have limited funds for a down payment
✔ Meet FHA qualification requirements
✔ Want a lower down-payment option
✔ Are purchasing within the applicable FHA loan limit
The "best" loan isn't necessarily the one with the lowest down payment. Compare interest rate, mortgage insurance, funding fees, closing costs, cash requirements, and long-term monthly payment.
A Smart First Step for St. Johns County Buyers
Before you start touring homes in Nocatee, RiverTown, SilverLeaf, St. Johns, Fruit Cove, Julington Creek, World Golf Village, or St. Augustine, talk with a lender and get fully pre-approved.
Knowing your financing options first helps you understand:
What you can afford → Which communities fit → Which homes fit → What your true monthly cost will be
And if you're a veteran or active-duty service member, make sure your lender evaluates your VA eligibility and entitlement before assuming FHA or conventional financing is your best option.
The Bottom Line
VA and FHA loans can both be valuable tools for buying a home in St. Johns County—but they're designed for different borrowers and have different costs and requirements.
For eligible military buyers, a VA loan can offer significant advantages, including potentially zero down payment and no monthly PMI. For qualifying buyers who need a lower-down-payment option, FHA financing can make a St. Johns County home more accessible.
The best place to start isn't with a house.
Start with your financing.
Call or text Gail DeMarco at 904-640-8000 when you're ready to explore homes and communities throughout St. Johns County.
Loan programs, eligibility requirements, interest rates, fees, insurance costs, and loan limits can change. This article is for general informational purposes and is not mortgage or financial advice. Speak with a licensed mortgage professional to determine which program you qualify for.